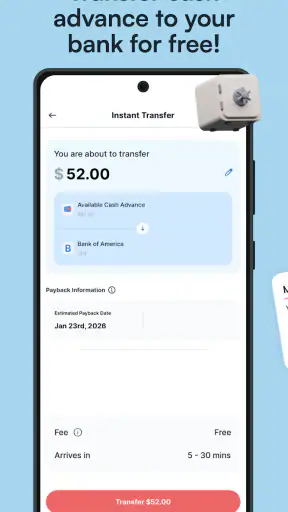
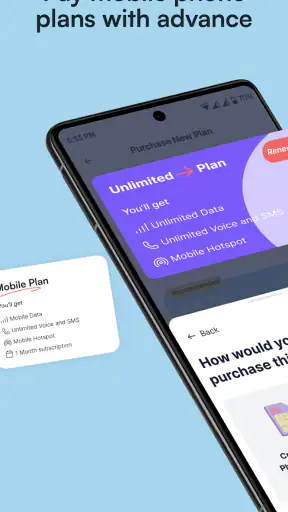
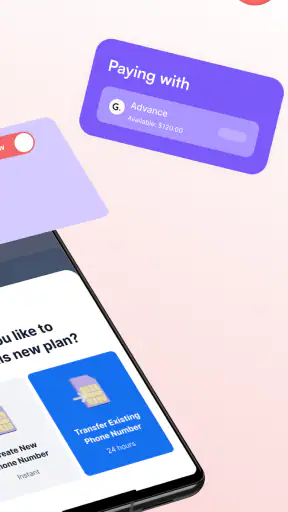
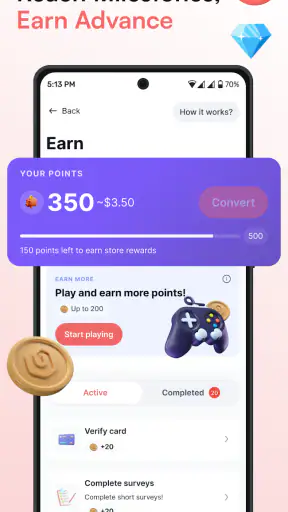
When an unexpected bill lands before payday, the hardest part is often not the amount itself but the timing. I tried Gerald - Cash Advance with that kind of short-term gap in mind, and I found an app that keeps the basic idea easy to understand: request access to cash through a phone rather than turning immediately to a credit card or a traditional loan application. It is a free finance app from Gerald Technologies, Inc., aimed at everyday users who need a temporary bridge.
The important distinction is that this is not a budgeting app, an investment platform, or a replacement for a bank account. Its purpose is narrower. You open it when your available money and your next income do not line up, then work through the in-app process to see whether an advance is available to you. That focused design makes the experience less intimidating than a conventional loan form, although it also means the app is most useful for a very specific problem.
I would describe the overall experience as quick to understand but not something to use casually. The store summary emphasizes fast access, no credit check, and no interest, which can sound reassuring when you are under pressure. In practice, the right way to approach it is as a short-term cash-flow tool. It can help with a one-off timing issue, but it should not become part of a recurring plan for covering ordinary expenses.
From a cash shortage to a completed request
Starting with the real problem
The most realistic starting point is a small, clearly defined shortage. Imagine that a utility payment is due today, your paycheck arrives later, and you already know exactly how the gap will be covered. In that situation, an advance can be easier to evaluate than a new credit card or a bank loan, both of which may create a longer relationship with borrowing than you intended.
Before opening the app, I would write down the bill, the amount needed, and the date when the money should become available again. That simple preparation matters because the app is designed around immediate access, and urgency can make people accept terms or timing without thinking through the repayment effect on the next pay cycle. Gerald can simplify the request, but it cannot decide whether borrowing is sensible for your household.
The app is free to install and carries an Everyone content rating, so it is presented as an accessible finance tool rather than a product restricted to a specialist audience. It supports Android devices running at least version 7.0. That makes it approachable for people using older phones, although I would still keep the operating system updated where possible because financial apps deserve extra care.
Moving through the request
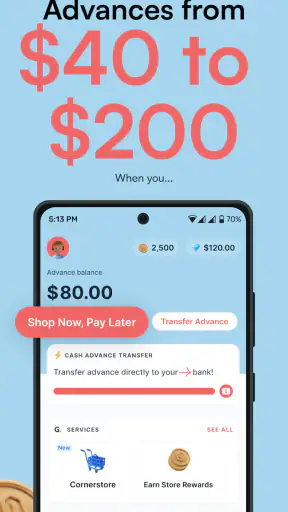
The first useful quality is that the purpose is visible quickly. You are not dropped into a crowded marketplace of financial products. The flow is centered on getting started, supplying the information needed for an eligibility decision, and reviewing what the app presents before continuing. I found that focus helpful because it reduces the temptation to browse or borrow more than the immediate problem requires.
My practical advice is to move slowly through each screen, even if the situation feels urgent. Check the amount, the expected timing, and any instructions attached to the request. A clean interface can make a financial decision feel harmless, but the consequences still depend on your own cash flow. Treat every confirmation button as a commitment rather than as another step in a casual signup.
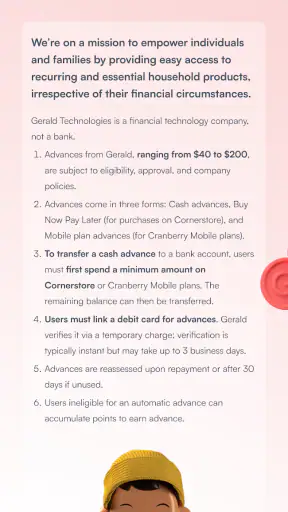
Gerald promotes the advance as involving no credit check and no interest. Those points make it different from many familiar borrowing options, especially for someone worried about a hard credit inquiry or an interest charge growing over time. They do not mean the service is consequence-free. The real question is whether the repayment or settlement arrangement fits your next income cycle without forcing you to borrow again.
That is one of the less obvious trade-offs here: avoiding interest does not automatically make an advance affordable. If the money solves one urgent payment but leaves you short for groceries, transport, or another automatic bill, the overall result may still be stressful. I would use the app only after checking the full week ahead, not just the bill that triggered the request.
Understanding the handoffs
A cash advance app is not an isolated calculator. Your request moves between your phone, the app’s account process, the information you provide, and the eventual delivery or repayment stage. Each handoff is a possible point of friction. A mismatch in personal details, an account that needs attention, or a timing issue can matter more than the polished first screen.
I recommend keeping your information consistent throughout the process and reading prompts rather than rushing past them. If the app asks you to connect or verify something, consider why that step is necessary and whether you are comfortable proceeding. Financial convenience is valuable, but it should not replace basic privacy awareness. I would also avoid completing a request on a shared device or an unsecured public connection.
The developer, Gerald Technologies, Inc., has built the experience around a direct consumer workflow rather than the slower, document-heavy feeling associated with a traditional lender. That is a strength when the need is immediate. The weakness is that users may expect the same predictability as a card payment or a bank transfer, even though short-term advance services can depend on eligibility and processing conditions.
For that reason, I would not begin the process minutes before a payment deadline. Start early enough to handle a verification prompt, correct an error, or choose another way to pay. The app may reduce the number of steps compared with applying for conventional credit, but it cannot remove every dependency between request, approval, and final access to funds.
What the outcome feels like
When the flow works for the situation, the main benefit is mental as much as financial. Instead of calling a bank, comparing loan pages, or putting an urgent expense on a high-cost card, you have one focused route to investigate. The app’s promise of no interest is especially relevant for someone who wants to avoid adding a revolving balance to an already tight budget.
I also like that the service is positioned for a temporary need rather than dressed up as a long-term financial solution. That makes it easier to set a personal boundary: use it for a defined emergency, then return to normal spending. The best result is not simply receiving cash. It is resolving the immediate bill without creating a second emergency when the next income arrives.
Its scale gives some context. Gerald has passed half a million installs, with an average rating of 4.4 from around ten thousand ratings and roughly 4.2 thousand written reviews. Those figures suggest that many people find the basic proposition useful, but they should not be treated as a guarantee that every request will feel smooth. Finance apps are highly personal; the same workflow can be convenient for one user and unsuitable for another.
Where the flow breaks down
The biggest limitation is the narrow margin for error. If you need money for a recurring shortfall, an advance may hide the underlying problem for a few days while making the next cycle harder. I would skip Gerald if rent, food, or essential transport already depends on borrowing each pay period. A conversation with a bank, a nonprofit adviser, or a creditor may be more appropriate in that situation.
I would also choose a different option when the expense is large, planned, or spread across several months. A conventional personal loan may be easier to compare for a larger structured need, while a credit card can be more practical for a purchase that offers strong consumer protections, provided the balance can be paid responsibly. Gerald makes more sense when the need is short, specific, and connected to a realistic incoming payment.
Another point of friction is psychological. The app’s simple presentation can make borrowing feel like a routine tap-through task. I found it necessary to create my own pause before requesting anything: identify the bill, confirm the amount, and ask what happens to the next budget after the advance is settled. That pause is not built into the convenience of the product; it is part of using it responsibly.
Users should also keep expectations realistic about speed. “Fast” is useful language for a short-term service, but an urgent need still deserves a backup plan. If a payment deadline cannot move, do not assume that opening the app guarantees money in hand at the exact moment you need it. Contacting the biller for a short extension may be less exciting, but it can be safer than relying on one untested route.
Who will get the most from it
I see the strongest fit for someone with regular income, a temporary timing mismatch, and a clear reason for requesting a modest advance. For example, if a necessary household charge arrives just before payday and the user has already checked that the following pay cycle will cover normal expenses, Gerald may offer a simpler alternative to interest-bearing credit.
It can also suit people who dislike traditional loan applications and want to investigate an option from a mobile device. The free entry point removes one barrier to trying the service, while the Everyone rating makes the app broadly approachable from a store perspective. Even so, accessibility should not be confused with universal suitability. A finance tool can be easy to open and still be wrong for your circumstances.
I would be more cautious for anyone with irregular income, several overdue bills, or no emergency buffer at all. If the expected repayment depends on an uncertain gig, a delayed invoice, or money that has not been confirmed, the advance may turn a possibility into an obligation. In that case, waiting, negotiating the bill, or seeking non-borrowing assistance may be the better decision.
Small habits that make the experience safer
My first tip is to request only the amount tied to the immediate expense. Do not use the availability of an advance as permission to expand the shopping list. Keeping the request small limits the damage if the next budget is tighter than expected and makes it easier to judge whether the app solved the original problem.
Second, take a screenshot or note of the confirmation details for your own records, without storing sensitive information somewhere exposed. Having a clear personal record helps when you are reviewing the next bank statement or checking whether the obligation has been resolved. It also prevents the common mistake of remembering the general idea but forgetting the exact timing.
Third, plan the handoff back into ordinary finances before accepting the money. I would move the expected repayment amount into a separate mental category immediately, even if it remains in the same bank account. That way, the advance is not mistaken for extra income. It is already assigned to a future responsibility.
Finally, update the app when a new version is available and protect the phone with a screen lock. Gerald’s current version is 69.0.9, and keeping software current is a sensible habit for any app handling financial information. It does not guarantee a perfect experience, but it reduces avoidable problems caused by outdated software or an exposed device.
How it compares with familiar alternatives
Compared with a credit card, Gerald is more focused on a short-term cash gap and is presented without interest. A card may offer broader purchasing flexibility, but that flexibility can encourage a balance to remain open. Gerald’s narrower purpose can be an advantage when you want a single, clearly defined bridge rather than another spending channel.
Compared with a bank loan, the app feels less formal and potentially less burdensome for a small urgent need. A bank may be the better choice for a larger amount, a fixed repayment schedule, or a customer who wants a longer record of terms to compare. The trade-off is that traditional products may take more time and involve credit considerations that Gerald specifically aims to avoid.
Compared with asking family or friends, the app offers privacy and independence, which many people value. On the other hand, a trusted person may be able to offer more flexible timing without a digital eligibility process. That does not make personal borrowing automatically better; it simply shows why Gerald should be judged against the whole set of realistic options, not only against expensive credit.
My final assessment after following the workflow
Gerald - Cash Advance is a focused finance app that can be useful when the problem is temporary, the amount is understood, and the next income is dependable. I appreciate the direct route, the free access, and the emphasis on no credit check and no interest. The experience is easier to grasp than many conventional borrowing journeys, especially when a user needs to investigate an option quickly.
Still, I would not recommend opening it with the expectation that an advance will fix a persistent budget deficit. Its convenience is strongest when paired with discipline: check the upcoming bills, request only what is necessary, read every handoff carefully, and keep a backup plan for deadlines. The app can remove friction from a short-term request, but it cannot remove the need to repay or the consequences of poor timing.
For a one-off cash-flow bridge, I think it is worth considering. For ongoing financial pressure, a different solution is more likely to help. That distinction is the key to using this app well: treat it as a narrowly targeted tool, not as spare income. With that mindset, Gerald can be a practical option for eligible users who want to handle an immediate gap without turning to interest-bearing credit.


